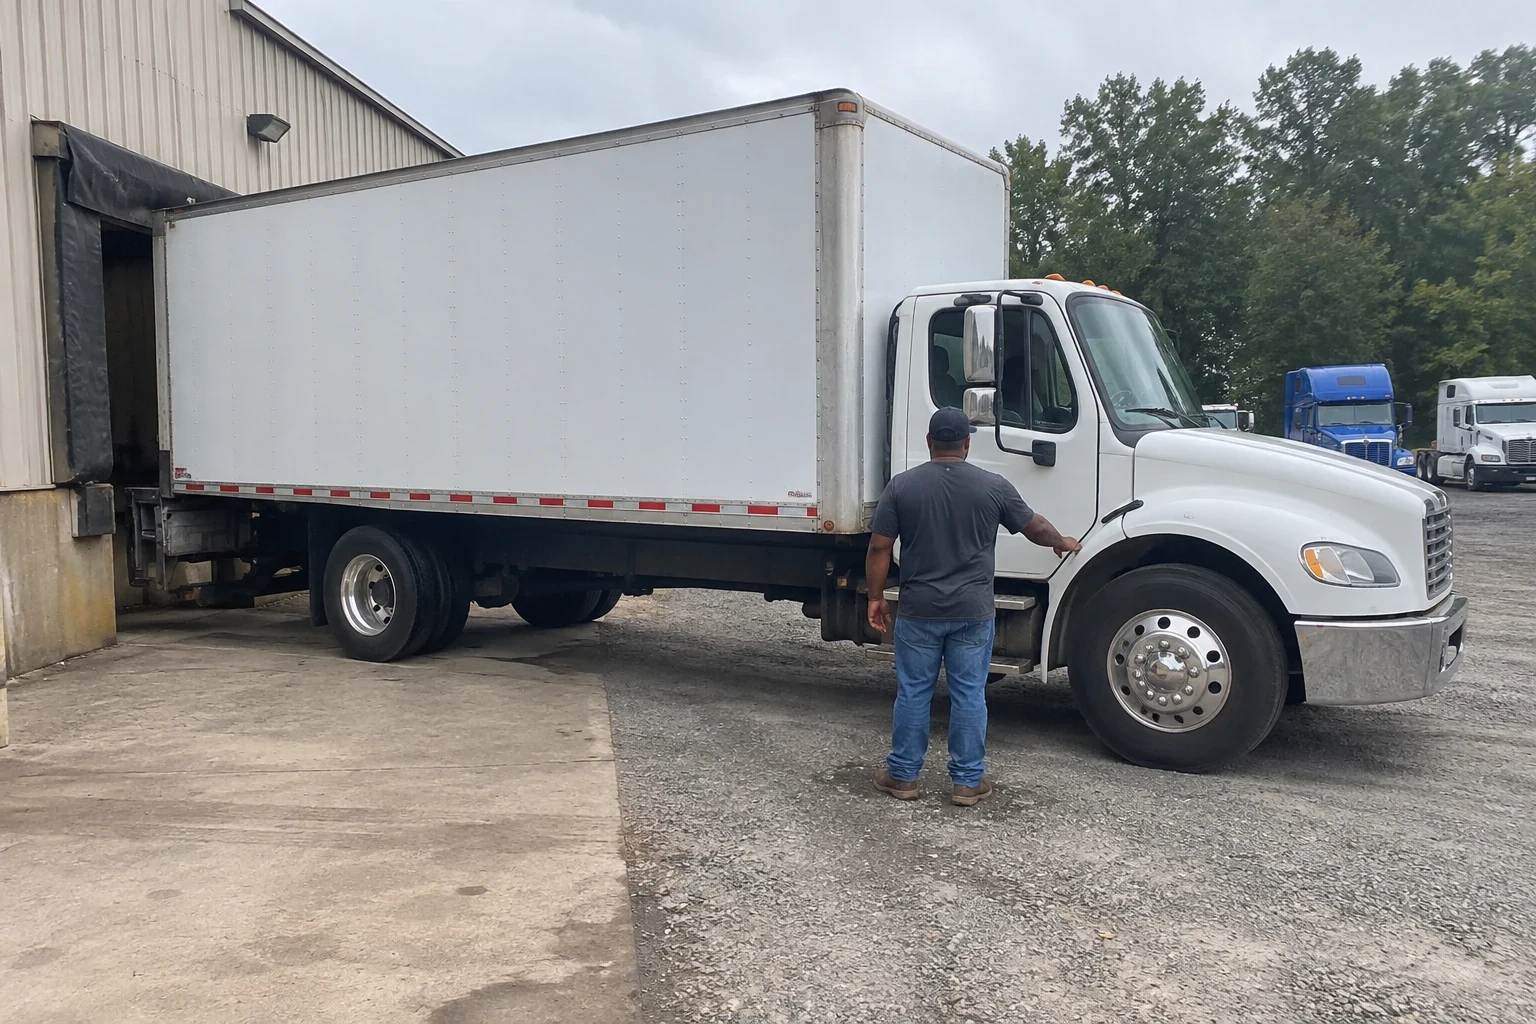
ServicesBox Truck Insurance
Box Truck Insurance in College Park
We cover box trucks running last-mile routes, furniture delivery, expedited freight and broker loads. Before we suggest anything, we look at your truck, your freight and the contracts you sign. Then we tell you plainly what you need and what you can skip.
Insurance built around how your box truck actually works
A box truck sits in an odd spot. It is too big for a personal auto policy and often too small for the way some carriers think about trucking. A lot of operators end up with coverage written for a semi or a pickup, and the gaps show up at claim time.
So we start by asking questions. What is the GVWR. Do you cross state lines. Do you run under your own MC authority or someone else's. Is there a liftgate or a reefer unit. Who are you hauling for, and what limits does that shipper or broker require. Those answers decide the policy, not the other way around.
We have been doing this for 5 years, and we are licensed for property and casualty insurance. We work with box truck owners from College Park out to Union City and Morrow, at our office or by phone and video.
What a box truck policy usually covers
Primary auto liability
Pays for injuries and damage you cause to others. This is the coverage tied to your DOT number and MC authority filings. Many brokers and last-mile contracts ask for limits above the federal minimum, so we check your contracts before we pick a number.
Physical damage
Covers your truck itself for collision, theft, fire and weather. We set the stated value from what the truck is really worth, including the box, liftgate and any refrigeration unit. Set it too low and a total loss leaves you short.
Cargo coverage
Protects the freight in the box. Furniture, appliances, electronics and refrigerated goods each come with their own exclusions. We read those exclusions with you so you know what is covered before the load goes on.
Non-trucking liability
If you are leased onto another carrier, their policy covers you under dispatch. Bobtail or non-trucking coverage fills the gap when you drive the truck off the clock.
Filings and certificates
We handle the insurance filings your authority needs and send a certificate of insurance to brokers and shippers when they ask for one.
Signs your box truck coverage needs a second look
- You moved from local to interstate
- Crossing state lines for hire changes the rules. You may need your own DOT number, MC authority and a federal filing your old policy never had.
- A broker turned down your certificate
- Load boards and last-mile programs set their own minimums. If a certificate of insurance came back rejected, your limits or cargo coverage likely fall short of what they require.
- You added a liftgate or reefer
- Equipment bolted onto the truck raises its value. If the stated value was never updated, a claim may not pay for it.
- Your cargo policy lists a lot of exclusions
- Some cheap cargo forms leave out unattended trucks, certain goods or reefer breakdown. If you have never read yours, it is worth a look.
- You hired a new driver
- Box trucks under 26,001 pounds often do not need a CDL, so newer drivers end up behind the wheel. Every driver needs to be listed and their record checked before they run.
How we work through it with you
- 1
We review what you have now
Send us your current policy, your truck details and any contracts you have signed. We go through it line by line and write down what we find.
- 2
We explain the findings plainly
We tell you where coverage is missing, where you are paying for something you do not need and where a contract asks for more than you carry. No sales pitch, just what the paperwork says.
- 3
We shop the coverage
We take your actual operation to carriers that write box trucks and bring back options side by side, with the differences spelled out.
- 4
We handle the filings and certificates
Once you choose, we take care of the filings and send certificates of insurance to the brokers and shippers you work with.
What moves your box truck premium
Premiums for box trucks swing a lot from one operator to the next. We go over each factor with you so the quote makes sense and nothing shows up later that you did not expect.
- Radius and routes
- A truck doing local deliveries around Hapeville and Forest Park is priced differently than one running freight across several states. Miles and radius both count.
- Driver records and experience
- Clean records and time behind the wheel of a box truck lower the cost. Recent violations or brand-new drivers raise it.
- What you haul
- Furniture moves, appliances, electronics and refrigerated freight carry more risk than general dry freight. The cargo coverage limit your contracts require also matters.
- Truck value and equipment
- A newer truck with a liftgate and reefer unit costs more to cover for physical damage than an older plain box.
- Time under your authority
- New authorities usually pay more in the first years. A clean loss history and steady operation help bring the premium down over time.
Box truck insurance questions
- Do I need commercial insurance if my box truck is under 26,000 pounds?
- Yes, if you use it for business. Weight decides whether you need a CDL, not whether you need commercial coverage. A personal auto policy will usually deny a claim on a truck hauling freight for pay.
- Do I need my own MC authority for a box truck?
- It depends on what you haul and where. If you carry freight for hire across state lines in a truck over 10,000 pounds, you generally need a DOT number and MC authority. If you are leased onto a carrier, you may run under theirs. We sort that out with you before we quote anything.
- Why does a last-mile program want higher limits than the law requires?
- Shippers and brokers carry their own risk and want your policy to absorb more of it. Their contract terms are separate from federal minimums. We read the contract and match your limits to it so your certificate gets accepted.
- Does cargo coverage pay if my reefer unit breaks down?
- Not always. Many cargo policies exclude spoilage from mechanical breakdown unless you add it. If you haul refrigerated freight, ask us to check for this before your next load.
- Can I add a second box truck later?
- Yes. We add it to your policy and update your filings and certificates. Once you have a few trucks, it may make sense to look at fleet truck insurance instead.
Get your box truck coverage checked
Tell us about your truck, your routes and who you haul for. We will go over what you have, explain what we find and give you your quote by phone.